Short version
Your first investment property is the one you learn the most from, and getting the order of the steps right counts most. Know what is possible to borrow, then what it costs you each week, then whose name it goes in. Choose the area, then the property. Have the contract put into plain words, with your solicitor acting for you. Then come finance, settlement and the first tenant, and a fresh look every year. Once you act, our concierge keeps your team in step.
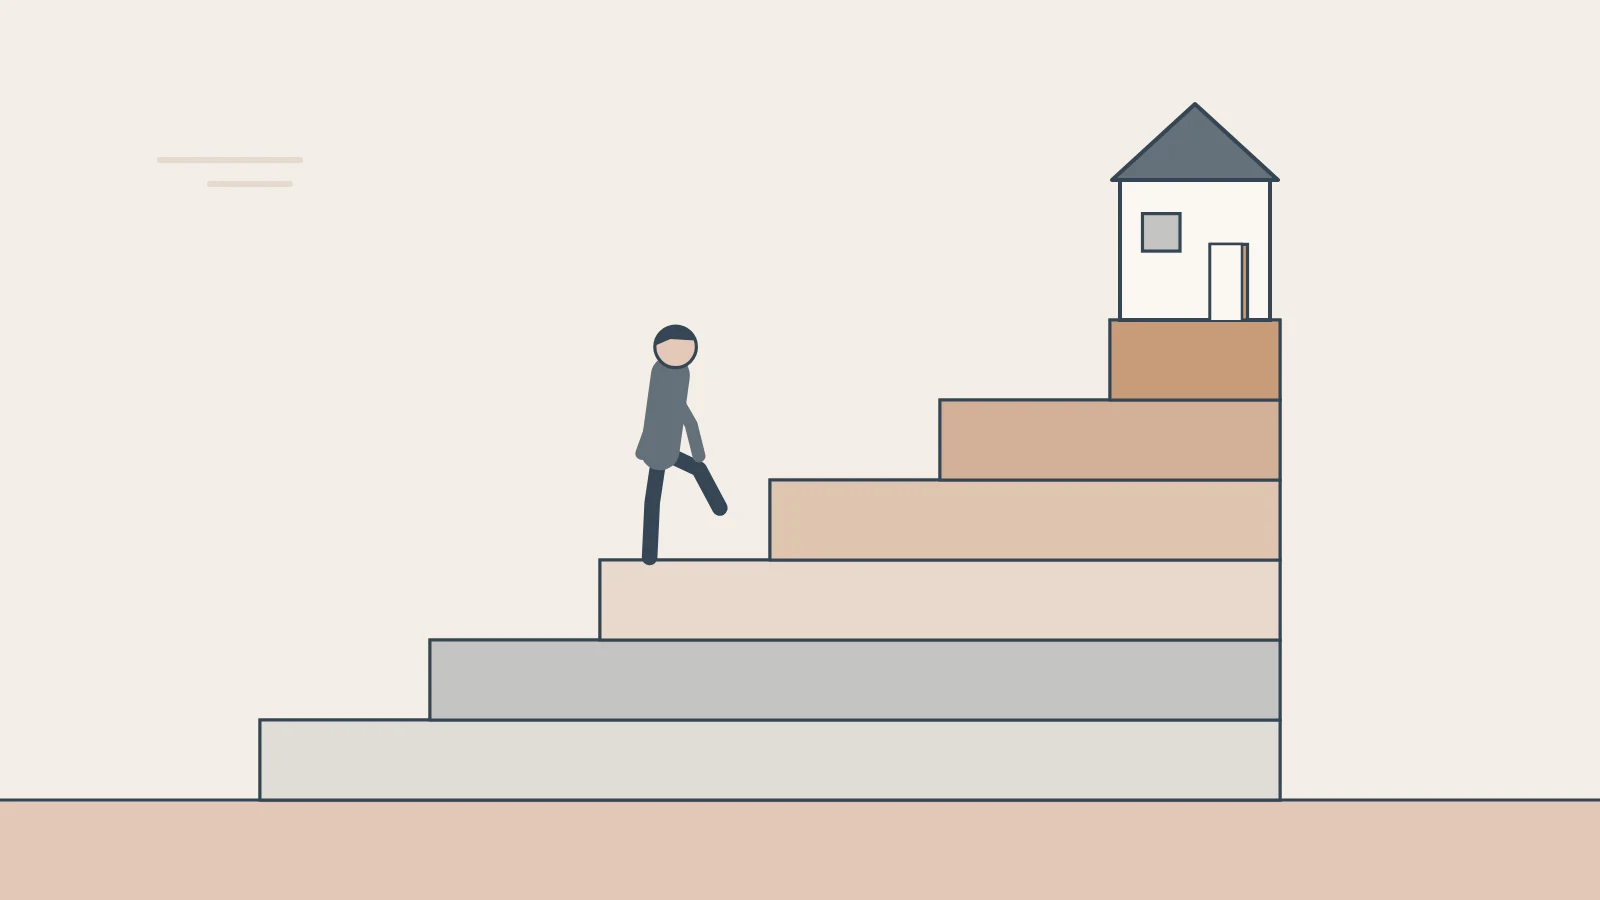
Your first investment property is the one you learn the most from, and the one where getting the order right counts most. Take the steps below in order, because each one shapes the next.
The first thing to do is establish your borrowing capacity. Not the figure a calculator gives you on a Sunday night: the figure a lender will stand behind. Lenders test your income against a rate three percentage points above the loan’s own rate, the buffer APRA kept in place on 28 May 2026, so the answer is often lower than people expect. That figure comes before any property. A broker can work it out with you. Home Buyers Club is run by my son, James. I explain how lenders arrive at it in How much can you borrow?
Every investment property has a weekly position: what the rent pays, what tax pays, and what you pay. Some carry themselves. Most cost their owner something in the early years. The question is not whether it costs you. It is whether the amount suits your life for the years you will hold it.
This is the step that is hardest to undo. Whoever is on the title claims the deductions while you hold it and carries the gain when you sell. Changing it afterwards usually means stamp duty and capital gains tax. I cover it in Own name, joint names or a trust?
Real estate is the land, and the land is where the growth comes from. So the area comes first: jobs, transport, supply and who rents there. Only then the property, and whether it suits the tenants that area attracts.
I read contracts with people before they sign, and I have read hundreds. Finance dates, building and pest conditions, and on a build the progress payments and what is fixed and what is not. A solicitor acts for you on the contract; my part is helping you comprehend what it says and what it means for you.
Formal approval, a valuation, then settlement. Before the keys arrive, the rental manager is lined up and a depreciation schedule is ordered from a quantity surveyor. On the new homes I’ve seen, the schedule has usually paid for itself in the first year.
Your first investment property is not a one-off decision. Rents rise, rates move, your income changes. Each year I look at where it stands with the owner, and whether it has built enough equity to help with the next one.
Mia, 31, found a townhouse she loved, paid for a building inspection and only then went to her bank to learn what she could borrow. The answer was $90,000 short. She lost the inspection fee and three months.
Her brother Sam started at step 1. He knew his figure, then his weekly comfort, then looked only at homes inside both. He bought in eight weeks. Same income, same market; a different order.
Someone with no buffer of savings, or whose income is about to change, may be better served by waiting a year and getting ready. Waiting with a plan is not the same as putting it off.
In real life the seven steps overlap. Once you act, our in-house concierge keeps the broker, lender, solicitor and builder in step, and tells you when each thing is done.
The first one is the one that teaches you the most. If you’d like each step ahead mapped on your own numbers, a Building Pathways does exactly that.
Nicholas Lockhart
Source: APRA, APRA maintains current macroprudential policy settings, 28 May 2026.