Short version
How many investment properties do you need to retire? Turn it around: retirement comes down to income. Start with the income you want, less what super and any pension will pay; that is what property has to produce. Rent pays you only after the loans are paid, so the real question is how many properties, held how long, with how much debt cleared by the day you stop.
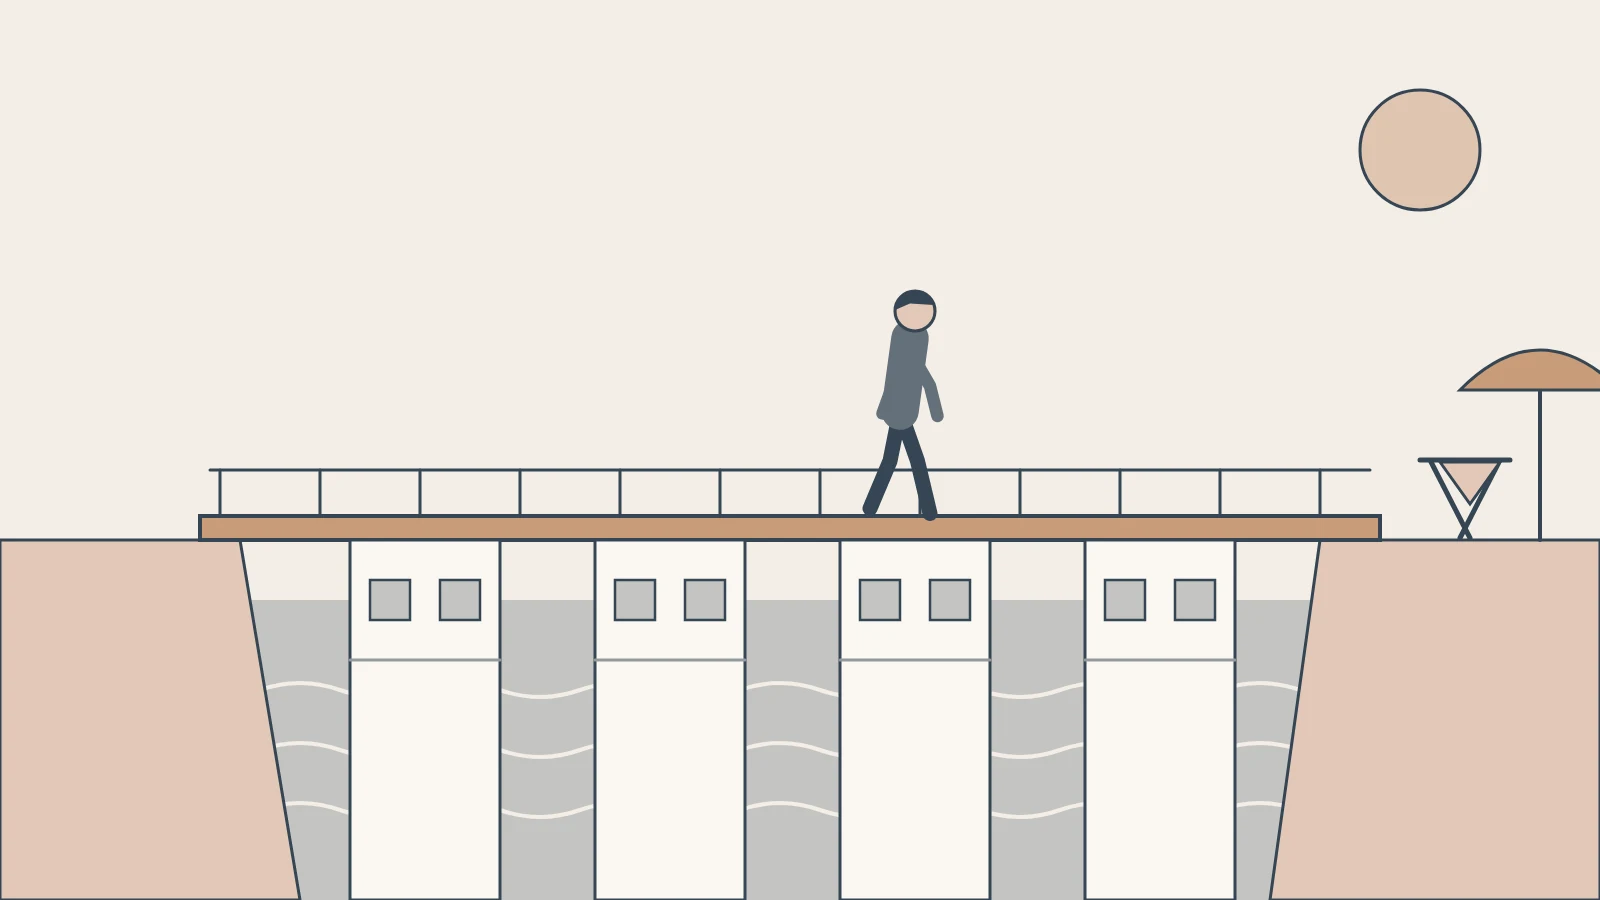
How many investment properties do you need to retire? I hear it every week, and I always turn it around. The windmills matter, because they can grow in value while they turn. In retirement, though, the question becomes how much energy they produce. Retirement comes down to income: the day you want to stop work, and the income to do it.
Start with the income
The Association of Superannuation Funds of Australia puts a comfortable retirement for a homeowning couple at $78,998 a year, as at the June quarter 2026. Your figure may be higher or lower. That figure, less whatever super and any pension will pay, is what the property has to produce.
Then the debt
Rent pays you only after the loans are paid. Three properties carrying large loans can produce less income than one with none. So the real question is how many properties, held how long, with how much debt cleared by the day you stop.
A couple want $79,000 a year. They expect super to pay $39,000 of it, so property has to find $40,000. These are round figures for illustration, not a forecast.
A debt-free home renting at $650 a week brings in $33,800 a year. After about 20 per cent in running costs, about $27,000 remains. One debt-free property is not enough; two would be, with room to spare.
To get there, they might buy four over fifteen years. At retirement, one path is to sell two to clear the loans on the other two; another is to keep all four and bring the debt down over the years before. Selling hands the future growth on those two to the next owner, so I set both paths side by side before anything is listed.
Tax and timing
Selling two to clear the other two brings capital gains tax, and the rules change from 1 July 2027. The year you sell, and whose name each property is in, change how much of the gain you keep. I explain it in Selling an investment property in retirement.
Who this does not suit
Someone five years from retirement with no equity cannot build this from scratch. There are other routes, and I model them with people in that position.
Four bought, two kept is a shape, not a plan; yours depends on your income, your timeline and what you hold now.
The right number is yours, not anyone else’s. A Building Pathways works it through on your own numbers, one step at a time.
Nicholas Lockhart