Short version
If you’re weighing a dual occupancy home, a duplex or a new build, the 2026 tax law touches your choice. Under the law today no home yet counts as new; the Tax Reform No. 3 Bill 2026 (passed by the House, not yet law) would exempt a newly built home. Building to hold and building to sell are taxed differently, and a build takes more of your time than an established home. Our concierge keeps your broker, lender, solicitor and builder in step, so you’re not chasing anyone.
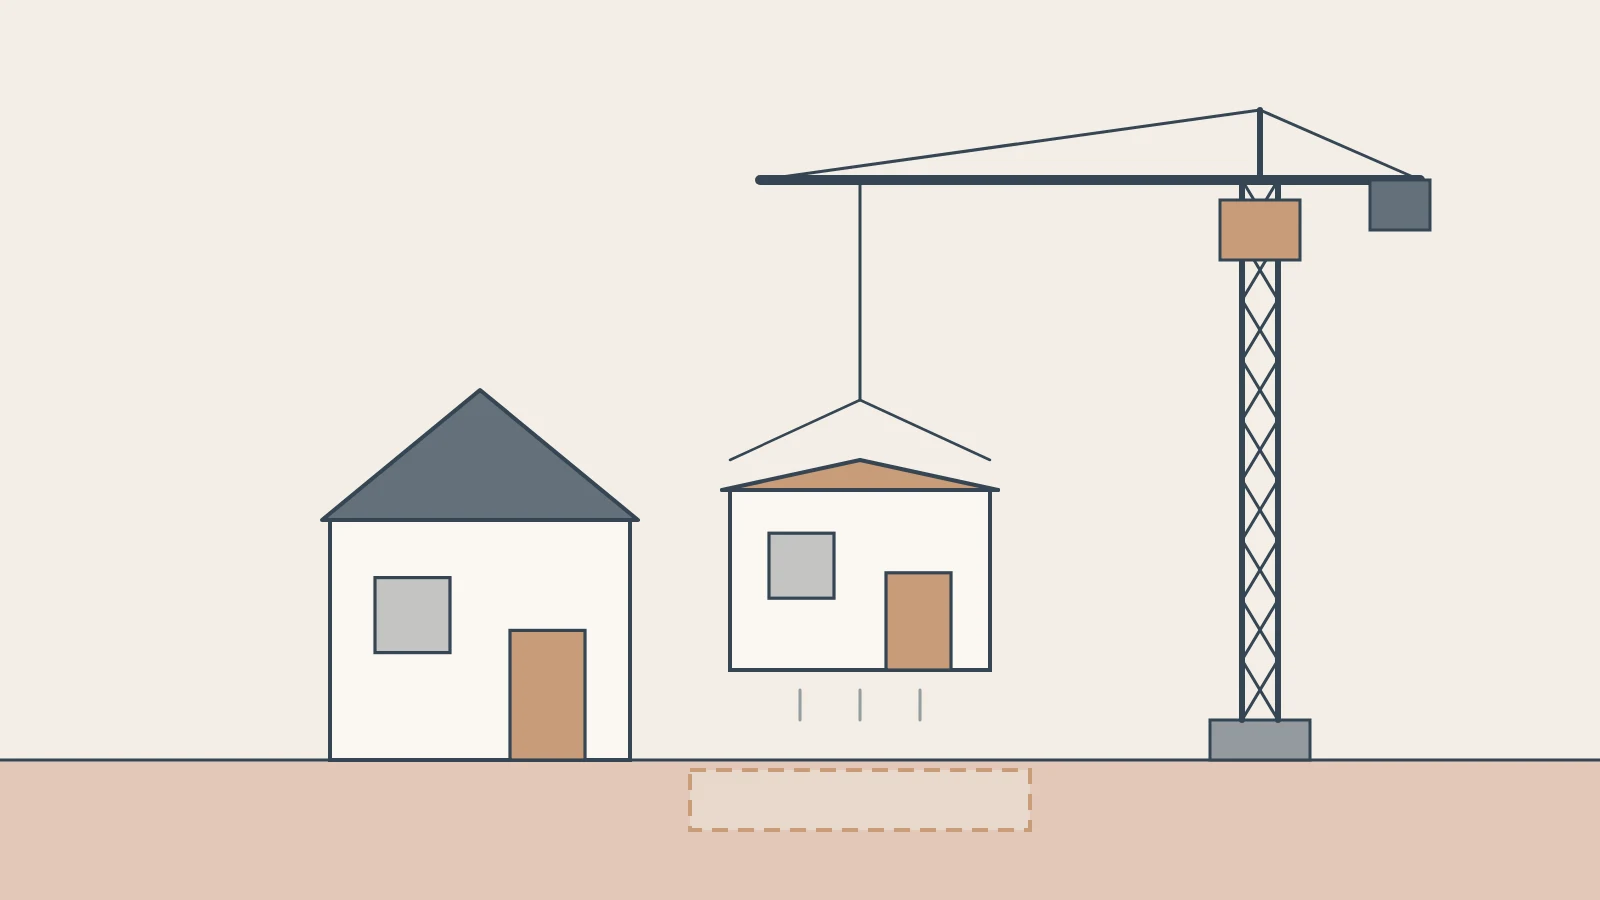
If you are weighing a dual occupancy home, a duplex or a new build, the law that changed in June 2026 touches your choice. Before it, building new was one choice among many. If the bill passes, it will have a place of its own.
Dual occupancy means two homes on one block of land. They can sit side by side, one behind the other, or under one roof, and each has its own entry, kitchen and bathroom. For an investor, it means two rents from one piece of land.
The words are used loosely, and each state uses its own. In general, a duplex is two homes joined by a shared wall, often built so each can be sold on its own title. Dual occupancy is the wider term: any two homes on one block, attached or not, and often on one title. Whether the two homes can be split onto separate titles depends on the council and the state, not on the name. Strata or Torrens title sets out what you would own either way.
Every state and council sets its own rules. Before you buy a block for dual occupancy, find out:
- whether the zoning allows two homes on that block;
- the minimum block size and street frontage;
- whether the two homes can be subdivided onto separate titles later;
- what parking, setbacks and open space each home needs;
- whether the approval is a quicker code path or a full application.
A block that looks right can fail on one of these, so check them in writing before you sign.
The law limits negative gearing to new builds from the 2027-28 income year, apart from homes already held at 7:30pm AEST on 12 May 2026, and keeps a choice on capital gains for new homes. But what counts as new is left to a Minister’s decision that has not been made, so under the law today no home is new. The Tax Reform No. 3 Bill 2026, passed by the House of Representatives on 29 October 2026 and not yet law, would exempt a newly built home. In broad terms, a new build adds a home that was not there before. I have set out the change in Negative gearing after 2026.
- House and land. A new home on a new block, often in an estate. The land contract and the build contract are usually separate.
- Dual occupancy. Two homes on one block, sometimes under one roof: two rents from one piece of land, often on one title.
- The mini developer. A larger block, or an older home on one, with two or more new homes built on it, held separately once titled. More approvals, a larger build, and more choice later: hold, refinance or sell each one on its own.
Two rents from one block can change the weekly figure. A dual occupancy home costs more to build than a single home, so the extra rent has to cover the interest on the extra money borrowed. That turns on the block, the build cost, the rate and the rents. I compared real homes side by side in Single home, dual income or duplex: a Tweed Heads comparison, and costed a build in Cost to build a duplex: a case study.
Building to hold and building to sell are taxed differently. A home built to hold is an investment, and its gain is taxed when it is sold. Homes built to sell can be treated as a business, with the profit taxed as income, and GST may apply. Where the line falls depends on the facts and on the intention at the start.
A new build needs more of your time and attention than an established home. Approvals take time. The loan is paid out in stages as the build goes up, with interest on each stage. Costs can rise and builders can run late, so the choice of builder deserves as much care as the choice of land. Someone has to keep the broker, lender, solicitor and builder in step, so each stage is ready when it falls due. With MRD, the concierge does it, so you are not chasing anyone and you hear when each step is done.
Take two investors with the same budget for land in the same street. One builds a single four-bedroom home. The other builds a dual occupancy home on a block approved for it: a main house and a smaller self‑contained home, each let separately. It costs more, and it collects two rents from one block. Whether the extra rent covers the interest on the extra money borrowed depends on the block, the build cost and the rate, and that is the first thing I would work out.
Building new does not suit someone who needs rent from the first week, or who could not carry the loan through a delay. It does not suit someone who would lose sleep over a council letter. And a small development is a project to see through, with decisions along the way, before it becomes an investment you hold.
If the bill passes, a new home will have the rules on its side, and a build to see through. Knowing both is how you decide whether it belongs in your plans.
A bigger project means more moving parts. A Building Pathways sets out each step, and what it could mean, before you start.
Nicholas Lockhart
Strata or Torrens title: what you own →
Negative gearing after 2026: what changed, and who it touches →
This article reflects the law as at 10 October 2026; an accountant can confirm how the rules apply to you.
Source: Australian Taxation Office, Tax reform - Boosting home ownership - Reforming negative gearing and capital gains tax (updated 29 June 2026); Treasury Laws Amendment (Tax Reform No. 1) Act 2026.