Short version
Positive or negative gearing describes one thing: whether the rent covers all the deductible costs, including the loan interest and depreciation. Cash flow positive is different again: after tax and depreciation, the property carries itself. A new home can be negatively geared on paper and still cash flow positive in your pocket. Under the law today, for a home bought after 7.30pm AEST on 12 May 2026, cash flow carries more of the weight in whether you can hold, from the 2027-28 income year. The Tax Reform No. 3 Bill 2026 (passed by the House, not yet law) would exempt a newly built home.
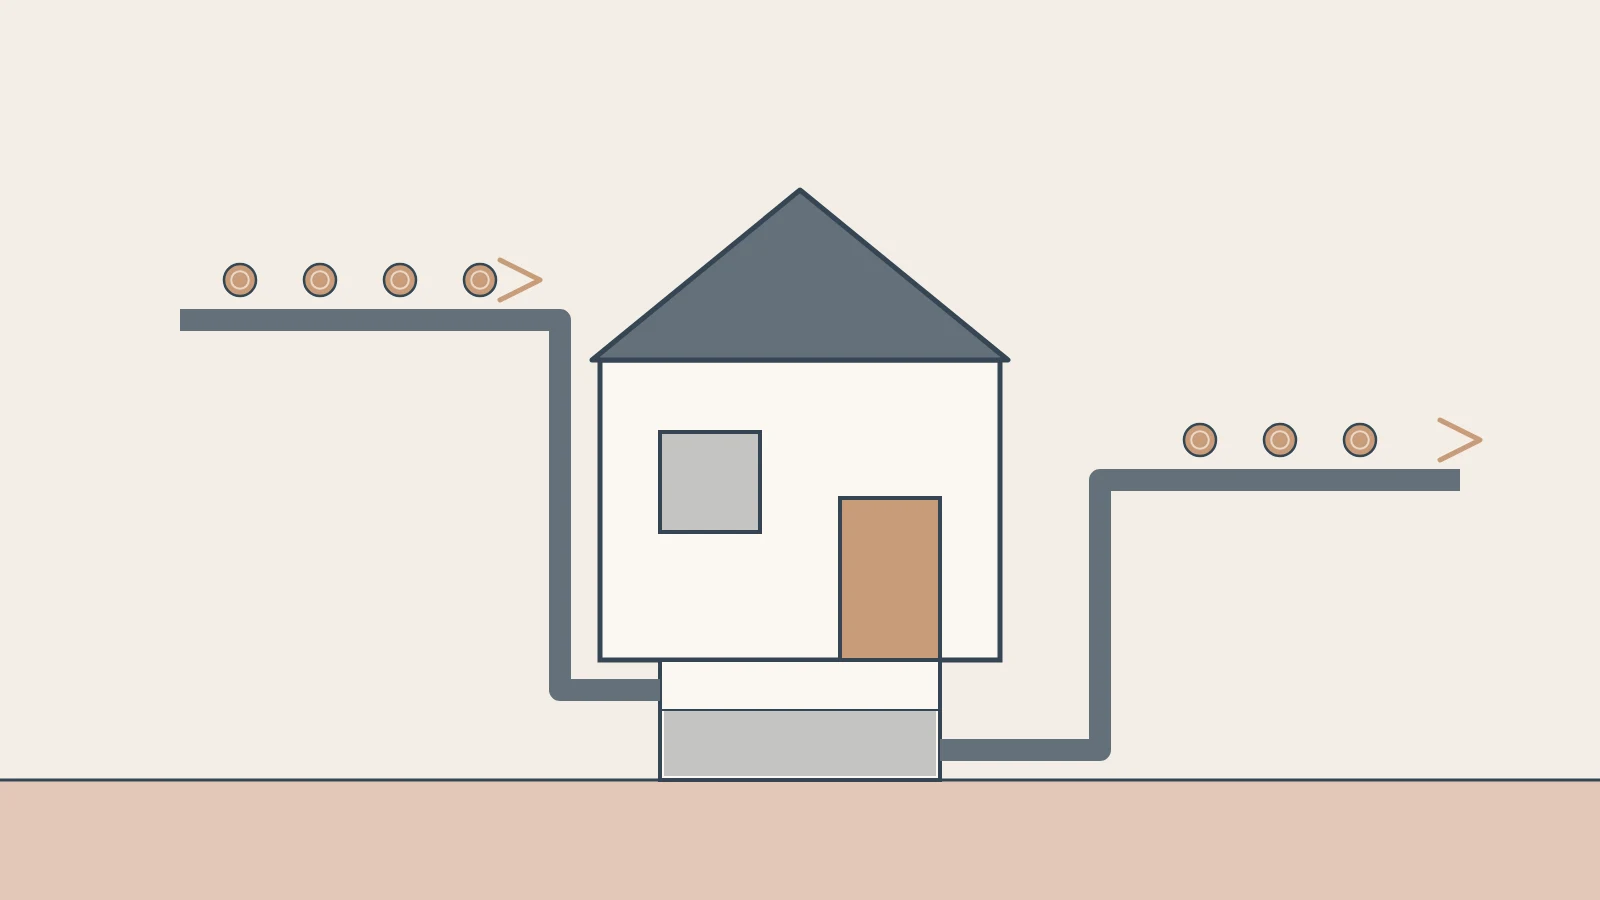
Positive or negative gearing describes one thing: whether the rent covers all the deductible costs, including the loan interest and depreciation. If it does not, the property is negatively geared and the loss is a tax deduction. If it does, it is positively geared and the profit is taxed. Cash flow positive is different again, and the difference is worth knowing.
Three positions
| Position | What it means | Who pays the gap |
|---|---|---|
| Negatively geared | Rent is less than the deductible costs, including interest and depreciation | You, partly offset by tax |
| Cash flow positive | After tax and depreciation, you pay nothing | No one: the property carries itself |
| Positively geared | Rent is more than all the deductible costs, including interest and depreciation | No gap; the surplus is taxed |
A new home can be negatively geared on paper and still cash flow positive in your pocket. Depreciation is a deduction you claim without spending the cash that year, so the tax saved can cover the shortfall.
Positively geared: what it takes
A property is positively geared when the year’s rent is more than all the deductible costs, including the loan interest and depreciation. Depreciation is not cash, so the first test most owners run is a cash one: the rent the cash costs need.
Take a home bought for $650,000 that rents for $600 a week, with running costs of $7,800 a year and an interest-only loan at 6.12%, the 30-year average rate.
- With an 80% loan of $520,000, the interest is $31,824 a year. Add the costs, and the rent the cash costs need is about $762 a week. At $600 a week, the owner is about $162 a week short before tax.
- With a 60% loan of $390,000, the interest is $23,868 a year. The rent the cash costs need is about $609 a week. At $600, the owner is about $9 a week short: almost there.
Four levers decide whether the rent gets there:
- The size of the deposit. The less you borrow, the less interest the rent has to cover. The cost is the money tied up in the deposit, which could be working somewhere else.
- The interest rate. A lower rate lowers the rent the cash costs need, and a rate rise raises it. Run the figures at a higher rate before you commit.
- The rent the land can earn. Two rents from one block, as with a dual income home or a duplex, can lift the rent faster than the price.
- The running costs. Management, insurance, rates and repairs all come off the rent. Some can be trimmed; most cannot.
Covering the cash costs is not the same as being positively geared for tax: once depreciation is counted, the same home can still show a loss on paper. The example is illustrative, not a forecast.
Why holding cost weighs more from 2027
From the 2027-28 income year, losses on established homes bought after 7:30pm AEST on 12 May 2026 can only be set against later residential rental income, or the gain on sale, not wages or other income. Under the law today no home yet counts as new, so a new build bought since is caught too. The Tax Reform No. 3 Bill 2026, passed by the House of Representatives on 29 October 2026 and not yet law, would exempt a newly built home. For an established home bought now, the tax refund that once softened the weekly cost is gone from the 2027-28 income year. Cash flow carries more of the weight in whether you can hold. The growth in the land is still, as I see it, the main reason to hold at all.
Properties that carry themselves
Dual-income homes and duplexes earn two rents from one piece of land, and they are where I see cash flow positive most often. I compared three real homes in a Tweed Heads comparison.
Home A rents for $560 a week and costs its owner $90 a week after tax. Home B rents for $720 a week and costs nothing. The owner of A needs $4,680 a year from wages; the owner of B does not.
Over ten years, the owner of B has $46,800 more in cash. If Home A sits on more land and grows faster, its owner may hold more equity to borrow against for the next property. Which comes out ahead depends on the growth, and no one can promise that. These are illustrative figures, not a forecast.
Who this does not suit
A higher earner with a long horizon may accept a weekly cost for a property with more land and stronger growth. A cost you can carry for ten years is a choice; one you cannot carry can force a sale.
Which side of that line a property sits on depends on the price, the rent, the loan, your tax and the rules it falls under. Know which side a property sits on before you sign.
The label counts for less than the weekly number. The Cash Flow Analysis shows yours.
Nicholas Lockhart
Negative gearing after 2026: what changed, and who it touches →
Single home, dual income or duplex: a Tweed Heads comparison →
How to calculate rental yield, and why yield alone can mislead you →
Source: Australian Taxation Office, Tax reform - Boosting home ownership - Reforming negative gearing and capital gains tax (updated 29 June 2026).