In short
- Rentvesting is renting the home you live in while you own investment property somewhere else.
- You live where you want to live, and you invest where the numbers work.
- A tenant helps pay for the property you own, and its running costs are generally deductible against the rent.
- The trade-offs are real: no home of your own for a time, and some first home and capital gains concessions you may give up.
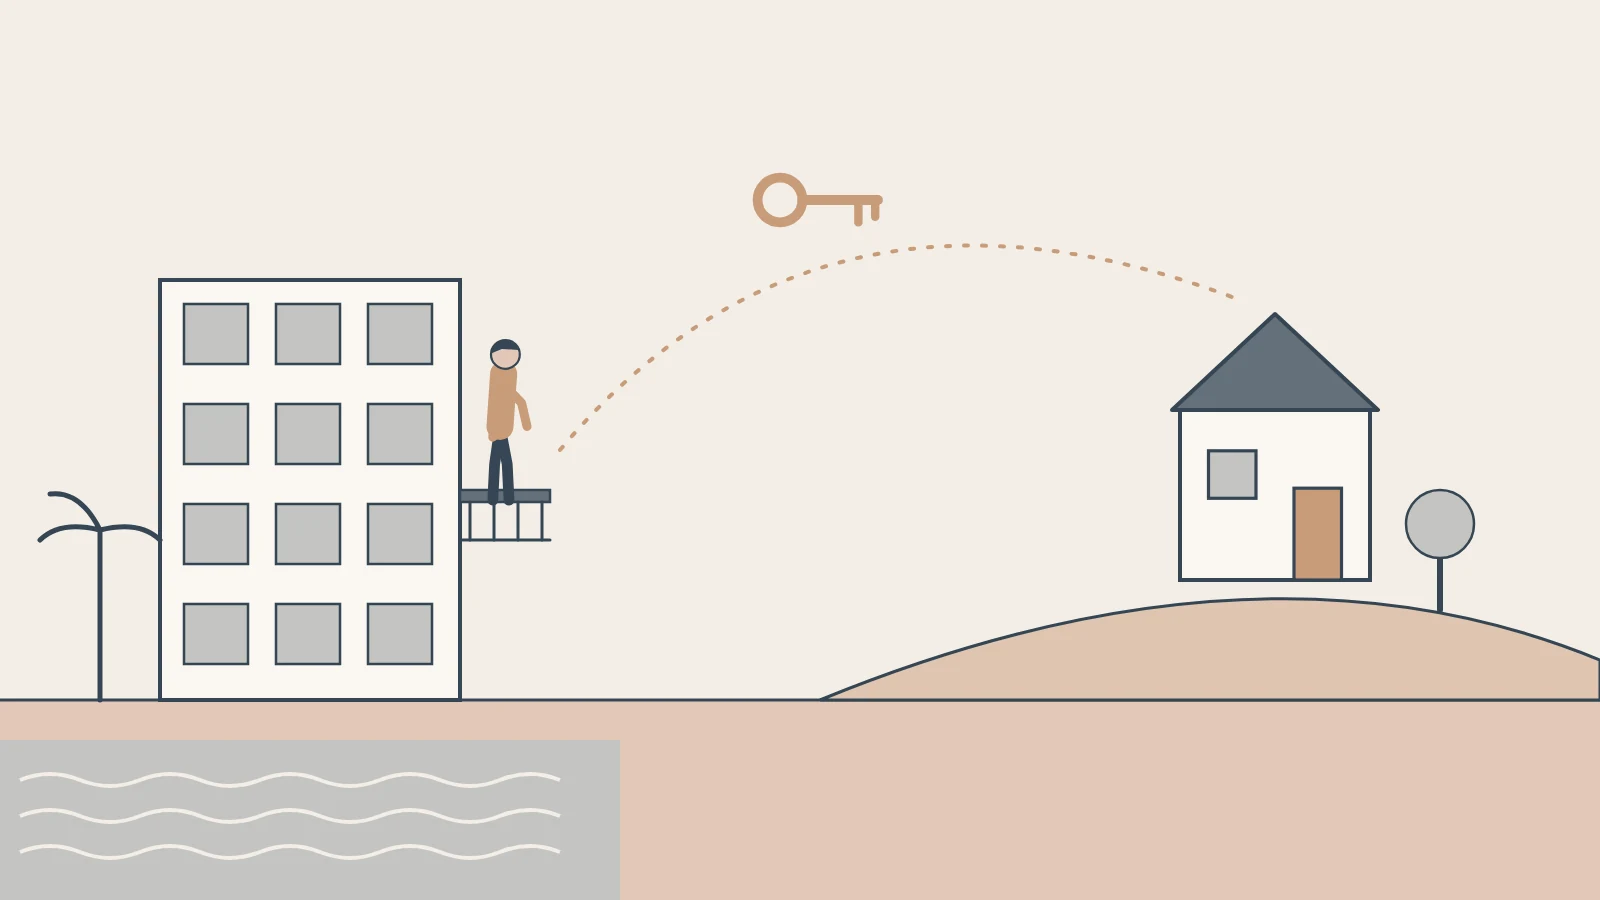
Rentvesting is renting the home you live in while you own investment property somewhere else. You live where you want to live, and you invest where the numbers work.
As a tenant you pay the rent, and that is all. The owner pays the insurance, the council rates, the maintenance and the interest on the loan. In your own home you pay every one of those, and none of it is tax deductible: not the interest, not the rates, not the repairs. You pay the bank principal and interest, and no tenant pays you rent.
An investment property turns that around. A tenant pays rent, and the property’s running costs are generally deductible against it. So the same dollar can work harder in an investment than in the home you live in.
Rentvesting separates two decisions people usually make together: where to live, and what to own. Seen clearly, each can be made on its own merits.
The pros
- You can live where you want to live, often in a home you could not afford to buy.
- Where homes are dear, rents are often low against the price, so renting there can cost less each week than owning.
- Your borrowing capacity goes into property a tenant helps pay for, so you start owning sooner.
- An investment’s running costs are generally deductible against its rent. Your own home’s costs are not.
The cons
- The home you live in is not yours, so the lease can end and the rent can rise.
- The property you invest in is not your main residence, so it does not get the capital gains exemption a home does.
- First home buyer schemes and concessions often require you to live in the home, so they may not apply to an investment. Owning an investment first can also rule you out of some first home grants later, because they require that you have never owned property.
- The Australian Government 5% Deposit Scheme lets eligible first home buyers purchase with a lower deposit and not pay Lenders Mortgage Insurance. For its first home guarantees you must be a first home buyer, or not have owned property in Australia in the ten years before you sign your home loan, and owning land counts. So an investment bought first can affect it.
- The hardest part is human nature: the wish to be in a home of your own. It can weigh heavily on a family, and it takes two people agreeing.
Both paths can build wealth. They put your money to work in different places, and the difference shows up week to week.
| Point | Rentvesting | Buying a home first |
|---|---|---|
| Where you live | Where you choose to rent | The home you buy |
| Rates, insurance and repairs on your home | Paid by the owner of your rental | Paid by you |
| The property you own | Earns rent from a tenant | Earns no rent |
| Its running costs | Generally deductible against the rent | Not deductible |
| Capital gains exemption on the property you own | Not a home, so it does not get it | A home can get it |
| First home schemes | Have their own rules; an investment may not qualify | Can apply |
In words: when you rentvest, you live where you choose to rent; when you buy a home first, you live in the home you buy. As a tenant, the rates, insurance and repairs on your home are paid by the owner; in your own home they are paid by you. The property a rentvestor owns earns rent from a tenant, and its running costs are generally deductible against that rent; your own home earns no rent and its costs are not deductible. The property a rentvestor owns is not their home, so it does not get the capital gains exemption a home can get. And first home schemes have their own rules, so an investment may not qualify, while they can apply when you buy your first home to live in.
A home is often bought on emotion, an investment on calculations. The better question is what your whole asset base is doing, the family home included, measured against your goals.
Renting for a season to get ahead has worked for people who kept to their calculations. It worked for us because we did the calculations, kept to them, and kept working them out again as everything changed.
It can be, for the right person at the right time. It tends to suit you if the home you want to live in costs far more than you can borrow, if the rent there is low against the price, and if you will invest what you save rather than spend it. It suits you less if you need the security of a home of your own, or a lease ending would upset your family.
On an investment property, costs such as the interest on the loan, council rates, and repairs and maintenance are generally deductible against the rent, as the ATO sets out. In your own home they are personal costs, and not deductible. Under the law today, from the 2027-28 income year a loss on a home bought after 7.30 pm on 12 May 2026 can’t be taken off your other income; it carries forward against later rent or gains on homes. The Tax Reform No. 3 Bill 2026, passed by the House of Representatives on 29 October 2026 and not yet law, would exempt a newly built home.
Some people start the other way round: they buy a home, live in it, then move out to rent somewhere else and let the home to a tenant. The capital gains rules have a part for this.
After you move out you can keep treating the home as your main residence for capital gains tax: up to 6 years if it is used to produce income such as rent, or indefinitely if not. While you do, no other property can be your main residence, except for up to 6 months when moving house, if you meet the conditions for that. The 6 years resets each time it again becomes your main residence.
So the order you do things in can count as much as the properties themselves. It is one to work through with your accountant before you move.
I did it for 16 years, from January 1999 to March 2015, and I don’t believe I would be where I am today had I not. In January 1999 we were renting, and we kept renting while we invested. The trade-off with my wife was simple: I made sure the homes we rented took pressure off her. The first was far beyond anything we could have bought. It would have cost about $350,000, when we could have afforded about $250,000, which from memory was the price then of a standard four-bedroom family home. It had five generous bedrooms upstairs, a pool for the kids, a yard, and a big living area downstairs that became my office.
The rent was well below what a loan, rates and maintenance would have cost us on a home of our own, and that freed our borrowing capacity. We bought our first two investment properties, let the tenants and the tax system help pay for them, and kept building from there, without the regularity of a wage.
Just before the global financial crisis, we contracted to buy an older home: a great location, not a great home. The plan was to move in, renovate and add a storey. Then the crisis hit. My broker rang to say the lender had been prepared to fund both the settlement and the renovation, and now it would fund the settlement only. So we settled, put a tenant in, and kept renting.
It was just as well we did. Credit stayed tight for years longer than we expected. Had we been living in that home, we might have had to sell it, or move out again at a cost. I chose not to move in until we were strong enough to make it a home worth living in.
In March 2015 we moved in. We left a beautiful, big, modern rental for an older home: a step down, but still a step forward. My wife has made it the home we dreamt of, and we are virtually living in the dream we had back then. My wife was incredibly gracious in agreeing to rent and again in staying the course after 2008. Had she not been, we would not have achieved what we have today.
Rentvesting does not suit someone who needs the security of a home of their own, or a family settled in a school who could not face a move at the end of a lease. It does not suit someone who would spend what they save on rent rather than invest it. And it takes patience: the property you hold may be in a place you rarely see.
Whether rentvesting suits you depends on where you want to live, what you earn and how long you can hold. Join our lessons by email and you get each step of building a portfolio in plain words, so you can set both paths side by side on your own numbers.
Renting where you live and owning where it pays has a cost and a benefit. The Cash Flow Analysis shows the owning side, week by week.
Nicholas Lockhart
Education only, not personal or financial advice.
Run your own numbers: the Cash Flow Analysis, and my free report, Property Cash Flow, Comprehended.
If the market falls soon after your first investment →
Negative gearing after 2026: what changed, and who it touches →
This article reflects the law as at 31 October 2026. An accountant and a broker can confirm what applies to you.
Sources: ATO, Rental expenses to claim (read 19 October 2026); ATO, Tax reform - Boosting home ownership - Reforming negative gearing and capital gains tax (updated 29 June 2026).; ITAA 1997, section 118-145 (the absence rule); Housing Australia, 5% Deposit Scheme